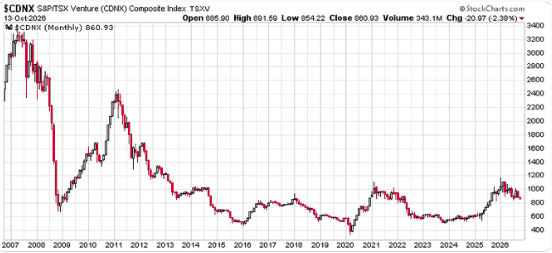
I became a stockbroker in 1984 after turning a small sum into a sizable profit as a private speculator—then losing it all through a penny-stock broker. That experience led me to Wall Street. Over the next 42 years, I speculated in high-risk, high-reward equities, primarily in the metals and mining sector. I made and lost millions twice, and some holdings ended up as certificates on the wall. Still, “Riverboat Pete” did quite well overall, especially over the past five years, even though the relevant market index remains roughly where it was 20 years ago.
As previously noted, I will stop discussing individual equities publicly after the first of the year. But because I believe the sector where I spent much of my career now offers an exceptional opportunity, I am taking one final big roll of the dice.
This is my personal speculative portfolio as of today:
- Northisle Copper & Gold (NTCPF,$2.11) I own 5.650,000 shares @$1.35
- Radisson Mining (RMRDF $.70) I own 5,000,000 @ $.70
- McFarlane Lake Mining (MLMLF $.29) I own 5,000,000 @ $.31
- Group Eleven Resources (GRVLF $.49) I own 3,100,000 @ $.52
Here’s why I personally hold these shares, fully aware that I could lose some or all my capital. Anyone investing in this sector must have both the financial capacity and the temperament to accept that risk.
I’ll begin with NTCPF, my largest and all-time favorite holding. In a sector where failure is common, an almost perfect combination of bullish factors has created the most compelling opportunity of my career. It is rare to own a stock that could become a mine while also offering exceptional exploration potential. Rarer still is having world-class management leading both efforts. Alex Davidson, who now actively oversees all aspects of exploration, was the single most important individual behind Barrick Gold’s growth from a small mining company into the world’s largest gold producer during his tenure. I cannot put a dollar value on what his involvement means to shareholders at this stage of the company’s development. Equally important, as the company rapidly approaches a milestone few achieve—a PFS—we are fortunate to have another highly experienced leader, Kevin O’Kane, at the COO helm.
With the company transitioning its exploration and geology teams to support its dual focus on exploration and project development, its corporate position has never been stronger. Neither its recent vice president of exploration nor Alex Davidson alone can fill the roles required on both sides, so I expect a vice president of geology to be appointed soon. With Alex and world-renowned VMS expert John Thompson assisting, the company has outstanding exploration potential through 2027 and beyond. Meanwhile, a PFS due in less than five months could drive a significant re-rating and is only one of many reasons I believe shareholders have an exceptionally bright future. The company is fully funded through the FFS, so its current share price does not constrain the growth ahead. I have continued adding to my position and hope to buy more whenever capital is available and the stock trades below US$3. I personally believe that, if I can hold for the full nine yards, the stock could still deliver a tenfold return from here.
Radisson Mining is a clear choice for me, especially now that Agnico Eagle is a major shareholder. Agnico Eagle recently acquired a substantial position, yet the stock now trades 15% below its entry price, making this a compelling speculation. Although I am biased as a shareholder, I do not expect the company to remain independent beyond the next 12–18 months. I see downside risk of 10%–20% and upside potential of 100%–200%.
McFarlane Lake Mining combines qualities we saw in Northern Superior, NTCPF, and RMRDF. Because I share Michael Gentile’s view that significant M&A activity is coming to this sector, I consider the company a prime acquisition target with the potential to deliver a manyfold return before any deal occurs.
Group Eleven Resources—In all my years, I have never seen a share price suffer because a company was too successful. Its drilling success rate is second to none, yet the market currently gives it little credit. Ultimately, as those results accumulate, I expect the company to earn a much higher valuation for succeeding where many others have not.
Every company in it is also held by Michael Gentile, the best investor and God-fearing man I have ever known, bar-none. In a presentation this past week, Michael covered many of the reasons I have cited for being bullish, along with several of his own that I fully share. I believe his case provides everything an aggressive speculator needs to know about this sector right now. The sector is undergoing a significant correction, but I have seen this happen many times during my 42 years in and around it. Volatility comes with the territory, and past corrections have created substantial wealth-building opportunities. I am betting heavily that this is another one.
If there’s one meme that describes my investing path versus most others at the time:
Early in 2026, this was the mood in the metals, mining and exploration sector:
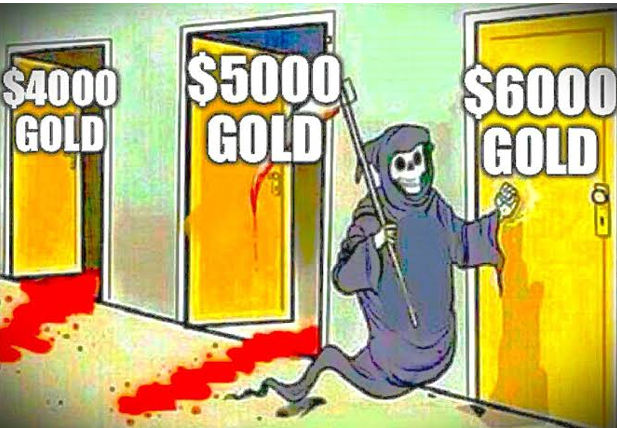
Now:

Me:

